
From 1 January 2027, German businesses whose total turnover in 2026 exceeded EUR 800,000 must issue structured electronic invoices (E-Rechnungen) for supplies to other businesses in Germany. From 1 January 2028, the obligation extends to all businesses. For Japanese, Chinese and Korean groups with a German subsidiary or branch, 2026 is the last full year to get invoicing systems ready.
1. Background: Germany’s B2B E-Invoicing Timeline
The obligation was introduced by the Growth Opportunities Act (Wachstumschancengesetz) of 27 March 2024, which amended Section 14 of the German VAT Act (UStG). The Federal Ministry of Finance (BMF) explained the rules in letters dated 15 October 2024 and 15 October 2025.
The rules are phased in. Receiving e-invoices has been mandatory since 2025; issuing them becomes mandatory in two steps.
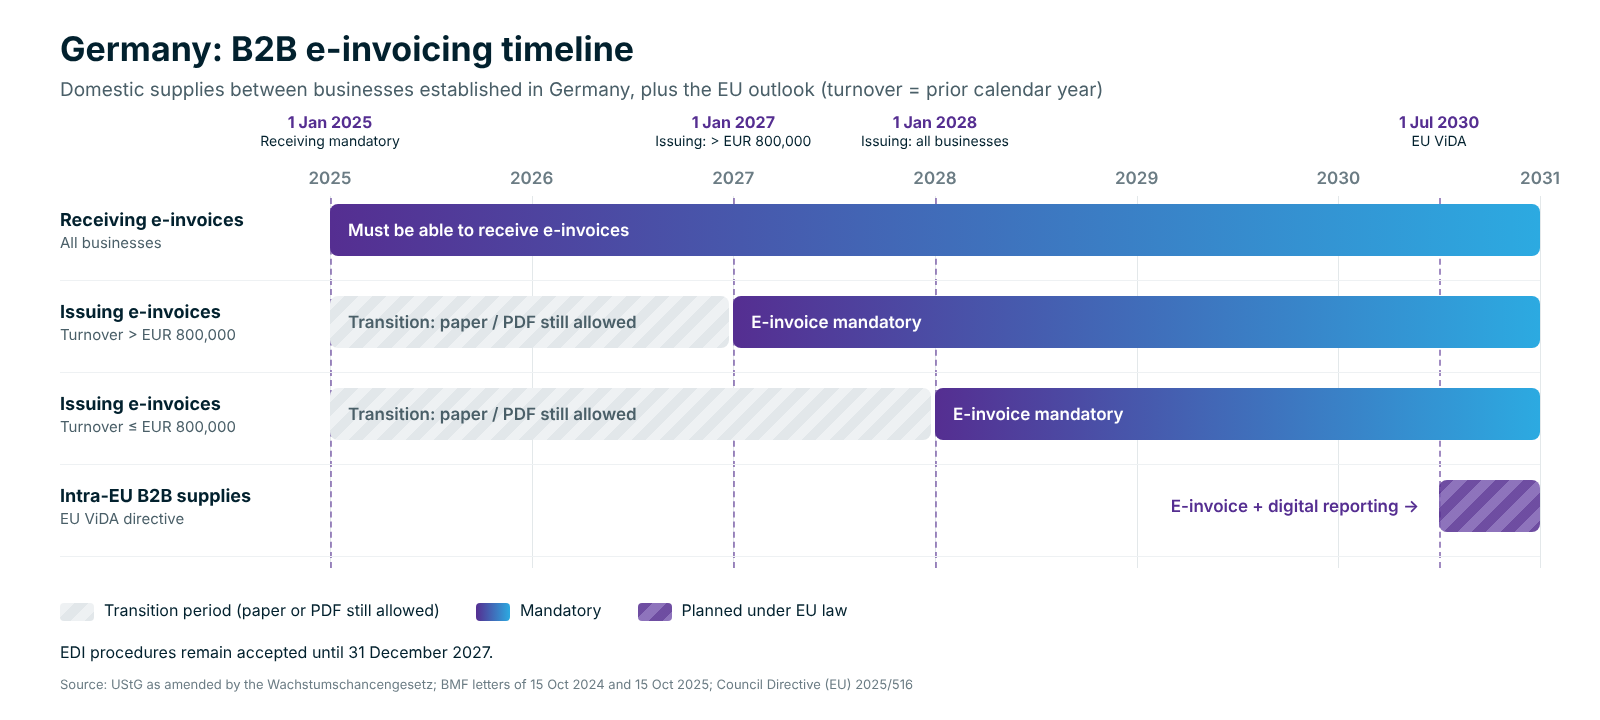
| Period | Receiving e-invoices | Issuing: prior-year turnover above EUR 800,000 | Issuing: prior-year turnover up to EUR 800,000 |
|---|---|---|---|
| 1 January 2025 – 31 December 2026 |
All businesses must be able to receive | Paper or other electronic formats (e.g., PDF) still allowed; PDF only with the customer’s consent | Same as left |
| 1 January 2027 – 31 December 2027 |
Same as above | E-invoice mandatory (existing EDI procedures still accepted) | Paper or PDF still allowed |
| From 1 January 2028 | Same as above | E-invoice mandatory | E-invoice mandatory |
“Must be able to receive” means a business cannot refuse an e-invoice from a German supplier and needs a way to accept, read and archive it, such as an email inbox plus a viewer or accounting software. There is no separate filing or registration.
EDI (Electronic Data Interchange) is the direct exchange of invoice data between two companies’ systems under an agreed technical format, common in the automotive and retail sectors. Existing EDI arrangements may continue until the end of 2027, even if they do not meet EN 16931.
The EUR 800,000 test uses the total turnover (Gesamtumsatz) of the preceding calendar year. For the 2027 obligation, the 2026 figure is decisive. Each German company is tested separately, so two sister companies can fall under different deadlines. Only in a German VAT group (Organschaft) is the turnover of the whole group used.
2. Who Is Affected: Key Points for Asian Subsidiaries
The obligation applies only when both the supplier and the customer are established in Germany (i.e., a domestic transaction between two German-established businesses). A business counts as established if it has its registered seat, its place of management or a VAT-relevant fixed establishment in Germany that is involved in the supply. A German VAT registration alone is not enough.
The test is applied to each transaction, not once per company. The same German subsidiary may need an e-invoice for one customer but not for another. The supplier may generally rely on the VAT number the customer provides.
This distinction matters for Japanese, Chinese and Korean groups, which often operate in Germany through several different structures.
| Typical structure | E-invoice obligation? |
|---|---|
| German subsidiary (GmbH) invoicing customers in Germany | Yes – receiving since 2025; issuing from 2027 or 2028, depending on turnover |
| German branch or other fixed establishment of an Asian or EU company, involved in the supply | Yes |
| Czech, Polish or other EU subsidiary with only a German VAT number (e.g., for warehousing or call-off stock) | No – no establishment in Germany (check whether the warehouse itself is a fixed establishment) |
| Parent company in Asia invoicing its German subsidiary | No – cross-border supply |
| German subsidiary invoicing customers in other EU countries or outside the EU | No – not a domestic supply |
| Supplies within a German VAT group (Organschaft) | No – not taxable supplies |
| German subsidiary invoicing a customer that provides a non-German VAT number (e.g., Czech) | Generally no – the supplier may rely on the VAT number provided; if the customer is in fact established in Germany, check case by case |
The following are also excluded, even for businesses that are otherwise in scope: invoices with a gross amount of up to EUR 250 (small-amount invoices), travel tickets and most VAT-exempt supplies. Small businesses under the German small-business scheme do not have to issue e-invoices but must be able to receive them.
Practical note for groups: Many Asian groups run the German entity on a group-wide ERP template. The German company code needs an output that meets the German standard, even if no other group company in Europe needs it yet.
3. What Qualifies as an E-Invoice
An e-invoice is a structured electronic invoice that follows the European standard EN 16931 and can be read automatically by the recipient’s system. A PDF is not an e-invoice, even when sent by email.
| Format | Qualifies as an e-invoice? |
|---|---|
| XRechnung (pure XML) | Yes |
| ZUGFeRD from version 2.0.1 (PDF with embedded XML) | Yes, except the MINIMUM and BASIC-WL profiles |
| Other EN 16931-compliant formats (e.g., Peppol BIS Billing) | Yes |
| PDF, scanned image, Word file | No – “other invoice” |
| Existing EDI procedures | Accepted until 31 December 2027 |
Three points from the BMF guidance are worth noting:
- All mandatory invoice details must be in the structured (XML) part. A reference to a PDF attachment or a link is not sufficient. In hybrid formats such as ZUGFeRD, the XML part prevails.
- No consent from the customer is needed to send an e-invoice. The transmission channel is not prescribed: email, download portals, interfaces and Peppol are all possible.
- E-invoices must be kept for 8 years, with the structured part unaltered.
Errors and input VAT
The BMF distinguishes three types of error. Format errors (the file does not follow EN 16931) mean the document is not an e-invoice. Business rule errors (e.g., inconsistent fields) only matter if they affect mandatory invoice details. Content errors (wrong or missing mandatory details) make the invoice incorrect. After the transition periods end, an invoice that is not a valid e-invoice puts the customer’s input VAT deduction at risk.
4. Do You Need a New System?
There is no government-certified software and no central government platform in Germany for B2B e-invoices. Invoices are exchanged directly between businesses. What is needed is software that can create, receive, validate and archive EN 16931 invoices.
| Option | What it covers |
|---|---|
| ERP add-on (e.g., SAP, Microsoft Dynamics) | Group ERP produces XRechnung or ZUGFeRD for the German entity |
| DATEV | DATEV E-Rechnungsplattform: e-invoice inbox in DATEV Unternehmen online, sending via the TRAFFIQX and Peppol networks, archiving in Belege online |
| E-invoicing service provider / Peppol access point | Conversion, sending and receiving, often linked to the existing ERP |
| Government tools | View only. The free ELSTER e-invoice viewer displays XML invoices in readable form; there is no government tool to create e-invoices |
If your German bookkeeping is outsourced to a tax adviser using DATEV, agree early on who receives incoming e-invoices, how they reach DATEV and who creates outgoing ones.
5. Beyond Domestic Invoices: EU ViDA and a German Reporting System
Today’s German obligation covers domestic B2B supplies only. Two further developments will widen it.
EU “VAT in the Digital Age” (ViDA). ViDA is an EU directive (Council Directive (EU) 2025/516 of 11 March 2025) that all Member States must implement. From 1 July 2030, invoices for intra-EU B2B supplies must be EN 16931 e-invoices, issued within 10 days, and their data must be reported to the tax authorities close to real time. This replaces today’s EC Sales Lists. Since April 2025, Member States can also introduce domestic e-invoicing without asking the EU for permission.
German reporting system. Germany plans a national transaction-based reporting system that uses e-invoice data. No start date has been fixed yet; 1 July 2030, in line with ViDA, is being discussed.
For Asian groups, this means e-invoicing will also reach cross-border flows, including supplies from a Czech or Polish subsidiary to a German customer.
6. Action Checklist
- Check the 2026 turnover of each German entity against EUR 800,000 (VAT group: the whole group).
- Map your German invoicing flows: which entities are established in Germany, and which customers are.
- Confirm your ERP or accounting system can issue XRechnung or ZUGFeRD and validate incoming files.
- Agree formats and channels with your main customers and suppliers.
- Align with your tax adviser on how e-invoices are received, imported into DATEV and booked.
- Update archiving so the XML is kept unaltered for 8 years.
- Report to headquarters on cost, timing and any IT budget needed, including the ViDA outlook for 2030.
Contact Us
Moore EU Asia works with the Moore member firms in Germany to help Japanese, Chinese and Korean companies review their German invoicing flows, check whether the e-invoicing rules apply and coordinate with IT and tax advisers. Please contact us if you have any questions.
This article provides general information as at 14 October 2026 and does not constitute advice on a specific tax position. The application to specific transactions must be assessed individually.

